
 See My Latest Article on HelloNation
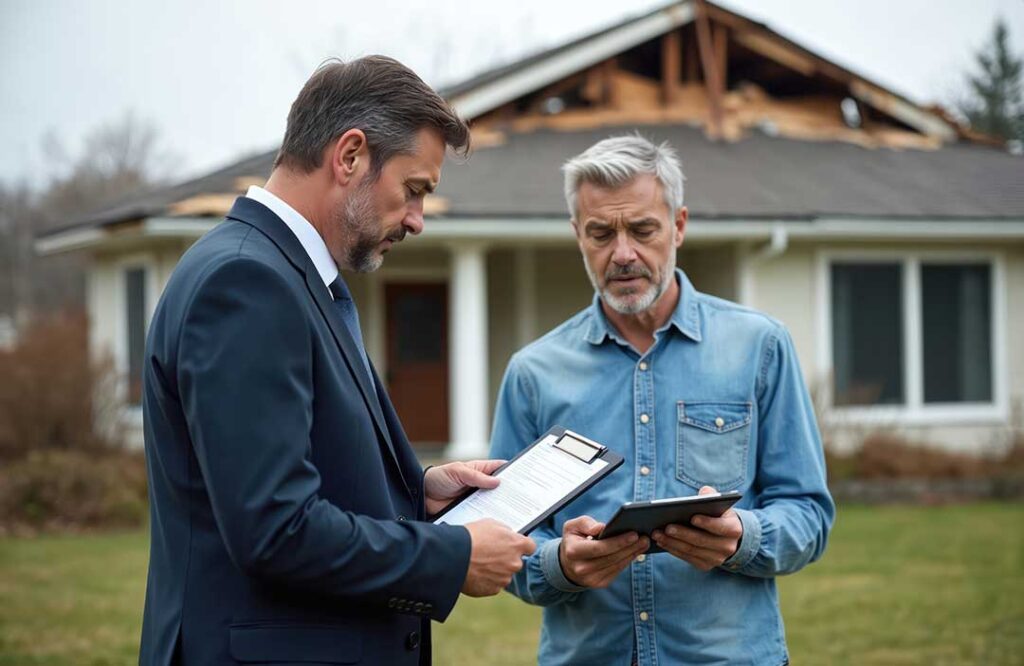
An insurance adjuster’s visit is a fact-finding inspection, not a test that requires a perfectly organized home or a polished explanation. The adjuster will usually document damage, ask when and how it occurred, review temporary repairs, and compare the observed conditions with the terms of the policy.
Good preparation helps create a complete record. It also makes it easier to explain what happened without guessing, overlooking rooms, or discarding evidence too soon.
What does an insurance adjuster do during a visit?
An insurance adjuster evaluates the reported loss for the insurance company. The visit may include an inspection of the home’s exterior, interior rooms, attached structures, personal property, and areas affected by temporary repairs.
The adjuster may:
- Photograph damaged surfaces, belongings, appliances, roofing, ceilings, flooring, and structural components
- Measure rooms or damaged sections
- Ask when the damage occurred and what conditions were present
- Look for signs of water entry, wind damage, impact, fire, theft, or other reported causes
- Review receipts, repair invoices, photographs, and lists of damaged property
- Ask whether anyone has made emergency repairs or removed damaged materials
- Explain what information is still needed to evaluate the claim
An adjuster’s estimate is not always the final settlement. Coverage decisions can depend on policy language, deductibles, exclusions, limits, depreciation, and whether additional damage is discovered later.
What should you do before the adjuster arrives?
Start by reviewing the claim information and policy documents you have available. Write down the claim number, the adjuster’s name, the date and time of the visit, and the best way to communicate with that person.
Prepare a short timeline. Include:
- The date or approximate date of the event
- What you first noticed
- Steps taken to prevent additional damage
- Repairs or cleanup already completed
- Items moved, discarded, or stored elsewhere
- Any changes in the condition since the claim was reported
A written timeline can be especially useful after severe thunderstorms, high winds, hail, or heavy rain, when multiple problems may appear over several days. In Ridgeland, MS, seasonal storms and moisture-related damage can affect roofs, ceilings, flooring, drywall, fencing, trees, and outdoor equipment. Record what was visible at the beginning, even if the damage later became more extensive.
How should damage be documented?
Photographs and video should be taken before cleanup whenever it is safe to do so. Capture both broad views and close-up details. A wide photograph can show where damage is located, while a close-up may show cracked materials, staining, broken components, or damaged personal property.
Useful documentation includes:
- Each affected room from several angles
- Exterior walls, roof edges, gutters, windows, doors, fences, and detached structures
- Water lines, stains, bulging drywall, warped flooring, and damaged insulation
- Furniture, electronics, clothing, tools, and other personal belongings
- Serial numbers, model information, and identifying marks
- Debris or damaged materials before they are removed
- Temporary measures such as tarps, boarded windows, fans, or water extraction equipment
Keep the original files when possible. Note the date, location, and a brief description for each photograph. If a phone automatically records this information, avoid editing the original file in a way that removes it.
Do not place yourself in danger to photograph a roof, unstable ceiling, standing water, exposed wiring, mold-like growth, or other hazardous conditions.
Should damaged items be thrown away?
Do not discard damaged items until they have been photographed and the insurance company has had a reasonable opportunity to inspect them, unless keeping them creates a health or safety risk.
Some materials may need to be removed quickly because of sewage, contaminated water, mold growth, insects, electrical hazards, or structural instability. Before disposal, photograph the item from multiple angles and make a written record of what it was, where it was located, how it was damaged, and when it was discarded.
Keep samples or portions of damaged materials when practical. For example, a damaged section of flooring or ceiling material may help document the type and extent of the loss. If an item must be discarded, retain receipts, photographs, repair records, or other proof of its condition and value.
What documents should be ready?
Place claim-related materials in one folder, either digital or paper. Helpful documents may include:
- The insurance policy and declarations page
- The claim number and prior correspondence
- Photographs or videos taken before the loss, if available
- A home inventory or list of damaged belongings
- Receipts, warranties, manuals, appraisals, or bank records
- Emergency repair invoices and receipts
- Estimates for necessary repairs
- Records of temporary living expenses, if the home cannot be occupied
- Notes from conversations with the insurance company, contractors, or adjuster
A home inventory does not need to be perfect. Begin with the most expensive, difficult-to-replace, or recently purchased items, then add details as records become available.
What should you tell the adjuster?
Be accurate, specific, and honest. Describe what was observed rather than making assumptions about the cause or coverage.
For example, it is better to say, “Water was visible on the ceiling below the attic after the storm,” than to state with certainty that a particular hidden component failed unless that has been verified.
Mention all affected areas, including damage that may be less obvious:
- Attics, crawl spaces, closets, and cabinets
- Insulation behind walls or above ceilings
- Flooring beneath rugs or furniture
- Electrical outlets, lighting, and built-in appliances
- Fencing, sheds, patios, and landscaping
- Personal property stored in garages or storage areas
If the adjuster does not inspect an area you believe is affected, politely point it out and ask that it be documented. Take your own notes about what was inspected and what was not.
What should you avoid doing during the inspection?
Avoid exaggerating, minimizing, or repairing everything before the damage is documented. Do not guess at purchase prices, dates, or causes. It is acceptable to say that you need to check your records.
Do not sign documents you do not understand. Some forms may authorize repairs, assign insurance benefits, release claims, or confirm a settlement. Read the entire document and ask what it does before signing.
Be cautious with unsolicited people who appear after a storm and pressure you to sign immediately. A person offering repair work, claim assistance, or payment-related services may have separate legal and financial interests. Taking time to review agreements can help protect your rights.
What if the adjuster’s estimate seems incomplete?
Ask for an itemized explanation of the estimate and compare it with your photographs, inventory, receipts, and repair information. If damage was missed, provide additional documentation and explain the issue in writing.
A difference of opinion does not automatically mean someone acted improperly. Construction costs, hidden damage, depreciation, policy exclusions, and the distinction between covered and uncovered causes can affect the calculation.
If disagreement continues, review the policy for procedures such as reconsideration, appraisal, mediation, or other dispute options. Keep copies of every submission and record the dates of communications. If the home is unsafe, the dispute involves a significant amount, or the policy language is difficult to interpret, legal or technical guidance may be appropriate.
How can households prepare for future claims?
Before the next loss, photograph major rooms and valuable belongings while they are in normal condition. Save digital copies of the policy, receipts, inventories, and repair records in a secure location outside the home.
In a community where heavy rain, wind, humidity, and fallen branches can create sudden property problems, basic preparation is practical rather than excessive. Knowing where shutoff valves are located, keeping emergency contact information accessible, and recording the condition of the property before damage occurs can make the inspection process more organized and more accurate.